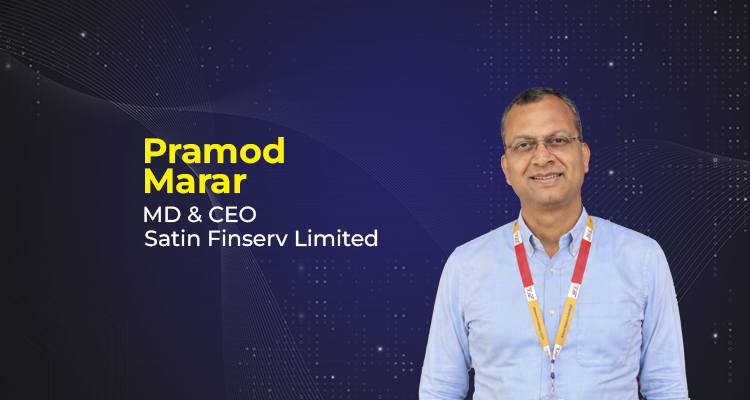
How is Satin Finserv evolving its lending approach to better address the changing financing needs of MSMEs and small businesses across India?
MSMEs today need more than just access to capital. Their requirements differ depending on the stage of the business, the sector they operate in and the way their cash flows work. For us, the focus is on understanding the business properly before looking at the loan. That means looking at how the enterprise earns, how predictable its cash flows are, what the capital will be used for and whether the repayment structure is aligned to the business cycle.
Different sectors and businesses operate very differently. A trader, a manufacturer and a service business will each have distinct working capital cycles and financing needs. Understanding these nuances helps us structure credit in a way that supports growth while remaining prudent.
As more MSMEs formalise and adopt digital systems, there is also much better information available than before. That helps lenders make more informed decisions and, importantly, serve businesses that may not always fit into traditional lending templates. The opportunity is to make credit more accessible, but in a manner that remains responsible. For us, sustainable growth in MSME lending will always depend on balancing customer needs with credit discipline.
What role do you see digital technologies and data-led lending playing in making credit more accessible, efficient and responsible for underserved businesses?
We see digital technologies and data-led lending as powerful enablers of financial inclusion, helping improve access to credit while making the lending process more efficient and informed. Digital documentation, transaction histories and better data can help us understand a customer faster and more accurately. It can improve turnaround time and streamline the lending process.
While technology is a powerful enabler, it should complement sound credit judgement rather than replace it. Data is valuable when it helps us develop a deeper understanding of a business. Is the cash flow sustainable? Is the borrowing linked to a genuine business requirement? Does the repayment plan align with the enterprise’s cash flow? These questions remain fundamental to responsible lending.
For us at SFL, the role of technology is not simply to accelerate the lending process. It should help make lending more accessible, more informed and more responsible. When used effectively, it enables lenders to serve a wider range of businesses while maintaining the discipline and prudence required for long-term, sustainable growth.
Green finance is becoming an important part of India’s growth story. What opportunities do you see for Satin Finserv in financing areas such as clean mobility, renewable energy and energy efficiency?
We see significant opportunities in clean mobility, renewable energy and energy efficiency, driven by the growing adoption of sustainable technologies and the increasing need for businesses to operate more efficiently. As these sectors evolve, there will be a greater need for financing solutions that support business expansion, technology adoption and innovation.
At Satin Finserv, sustainable lending is already an area of critical focus, and we are actively supporting businesses across segments such as electric mobility, solar energy and energy efficiency. We believe these sectors have the potential to create both economic and environmental value while contributing to India’s long-term growth and sustainability transition.
We also recognise that the transition to a greener economy requires more than the availability of capital. Businesses need financing partners who understand their operating models, growth potential and evolving requirements. We believe the most meaningful opportunities will come from supporting businesses that are able to combine commercial viability with measurable environmental impact. Our focus is on combining a customer-centric approach with prudent lending practices to support enterprises as they scale sustainably, while building a resilient and responsible lending portfolio.
With your experience across corporate banking, microfinance, fintech and entrepreneurship, what are the key lessons that have shaped your approach to building sustainable and scalable financial businesses?
One lesson that has stayed with me across different roles is that scale cannot come at the cost of fundamentals. Whether you are in corporate banking, MSME finance or fintech, the basics remain the same. You have to understand the customer, maintain discipline in underwriting, identify risk early and ensure that the business model remains sound as you grow complying with the law of the land.
Another key learning is that sustainable growth requires a balance between ambition and prudence. Access to capital can accelerate expansion, but lasting success depends on deploying that capital effectively, adapting to changing market conditions and managing risks responsibly.
The same principles apply to entrepreneurship and climate innovation. A promising idea must solve a real problem, work under practical conditions and have a viable pathway to scale. Access to capital, mentorship and markets can play a critical role in helping businesses translate promising ideas into sustainable and impactful enterprises.
Looking ahead, what are the biggest opportunities and challenges you see for Satin Finserv as it seeks to combine financial inclusion, MSME growth and sustainability?
We see a significant opportunity at the intersection of financial inclusion, MSME growth and sustainability. India’s MSMEs require access to timely and appropriate finance to expand their businesses, improve productivity and strengthen competitiveness. At the same time, there is increasing potential to support enterprises in adopting more efficient and sustainable practices that enhance both resilience and long-term performance.
The challenge is to expand access while maintaining portfolio quality and sound credit discipline. MSMEs operate across diverse sectors and business models, making it essential to assess cash flows, viability and repayment capacity carefully. Sustainable growth can only be achieved when credit expansion is supported by prudent risk management.
Given the nascency of the Sustainability ecosystem, the biggest opportunity that we see for a Financial Institution is to act as an enabler in strengthening this ecosystem. With this objective in mind, we have launched “Sankalp by Satin Finserv” to ensure that breakthrough solutions addressing critical sustainability challenges are identified, encouraged, and connected with the expertise, networks, and opportunities needed to translate innovation into measurable impact.
Enjoyed this interview? Now imagine yours. Write to:
jeevika@thefoundermedia.in